


A larger lump sum due at the end of a lease-to-own plan, which lowers your monthly payments during the term.
Balloon (Final Term) Payments on Lease-to-Own Cars: How They Work
24/7 Support
Always here when you need help
Free Delivery
Delivered at your preferred location
Best Rates
Competitive pricing for every trip
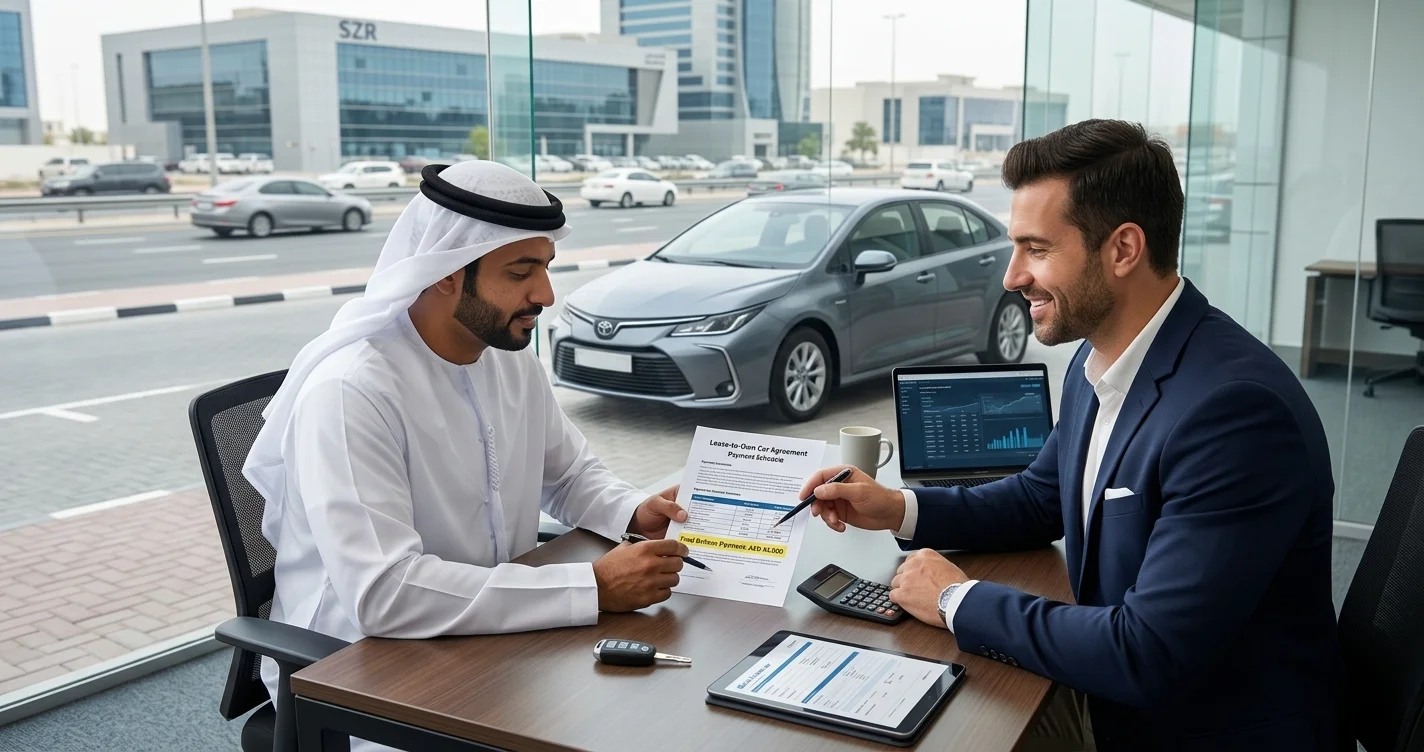
Quick answer: A balloon payment (also called a final term payment) is a larger lump sum due at the end of a lease-to-own plan. Deferring part of the car's cost to the end lowers your monthly payments during the term. When the balloon falls due, you can usually pay it to own the car, refinance it, or return the car, depending on your plan.
Two people lease the same AED 90,000 car over four years. One pays noticeably less each month than the other.
Same car. Same term. The difference is a balloon payment.
It's one of the most useful features of lease-to-own plans, and one of the most misunderstood. This guide explains how it works, when it makes sense and what to watch for. For an overview of all our plans, see Quick Lease personal lease plans.
What is a balloon payment?
A balloon payment is a lump sum due at the end of your agreement. Instead of spreading the car's full cost evenly across every month, part of it is set aside to be paid at the end.
You'll hear it called a final term payment, a balloon, or sometimes a residual value payment. In practice, they describe the same idea: lower monthly payments now, a larger payment later.
A worked example
Here's a simplified illustration. Real plans include finance charges and may include insurance and servicing, so actual numbers differ.
| Without balloon | With 30% balloon | |
|---|---|---|
| Car value | AED 90,000 | AED 90,000 |
| Term | 48 months | 48 months |
| Amount spread across monthly payments | AED 90,000 | AED 63,000 |
| Balloon due at end | AED 0 | AED 27,000 |
| Monthly payment (before finance charges) | ~AED 1,875 | ~AED 1,313 |
In this example, the balloon reduces the monthly payment by about AED 560 before finance charges. The trade-off is the AED 27,000 due at the end.
Why choose a balloon payment?
- Lower monthly payments. Easier on your monthly budget, or lets you drive a better car for the same payment.
- Flexibility at the end. You decide later whether to own the car.
- Matches expected income growth. Useful if you expect a raise, bonus or end-of-service payout by the end of the term.
Who is a balloon payment right for?
| You might suit a balloon if... | You might avoid a balloon if... |
|---|---|
| You want lower monthly payments | You want the lowest total cost |
| You expect a lump sum later | You have no plan for the final payment |
| You're unsure whether you'll keep the car | You definitely want to own it with no lump sum |
| You'd like a better car for the same monthly budget | You prefer simple, even payments |
Quick Lease's final-term lease-to-own plan is built around this structure. If you're comparing it with other plans, read our guide to car lease eligibility by salary, which explains why lower monthly payments can help approval.
What are the risks?
You need a plan for the lump sum. If you want to keep the car, the balloon must be paid or refinanced. Start saving or planning from day one.
Total cost can be higher. Because more of the balance stays outstanding for longer, total finance charges can be higher than a plan without a balloon.
The car's value may be lower than the balloon. If the car is worth less than the balloon at the end, paying it to own the car may not make financial sense. Check the market value before deciding.
Your options when the balloon is due
- Pay the balloon and take full ownership.
- Refinance the balloon through a bank or provider, if available, spreading it over a new term.
- Return the car, if your plan allows, and walk away or start a new lease.
- Sell the car and use the proceeds to settle the balloon, where the plan permits.
Our guide to end of car lease options in the UAE covers each path in more detail.
Questions to ask before signing
- What percentage of the car's value is the balloon?
- What are my exact options when it falls due?
- Can I pay part of the balloon early?
- Is refinancing available, and at what rate?
- What happens if the car's market value is below the balloon?
Key takeaways
- A balloon payment is a lump sum at the end of a lease-to-own plan that lowers monthly payments.
- It adds flexibility but can increase total cost.
- Plan for the final payment from the start.
- At the end, you can usually pay, refinance, return or sell, depending on the plan.
Sources: Quick Lease lease-to-own plan structures. Example figures are illustrative and exclude finance charges. Last updated: 30 October 2026.
FAQ
Frequently Asked Questions
Frequently asked questions about this article.
Need more help?
Contact us